



1. Introduction
This is a briefing for UK banks, building societies, challengers and the suppliers who work with them. The short version: yes, vibe coders can build parts of banking software, and the parts they should not touch are the parts the PRA and FCA care about most.
Regulators first, because they frame everything. They expect firms to stay accountable for outsourced work, to remain within impact tolerances for important business services and to deliver good outcomes under the Consumer Duty. None of that changes because a supplier used AI. It does mean you should hire vibe coders for banking software in UK projects only when they can show controls, not just speed.
ArixLabs builds with vibe coding, with every AI-drafted change reviewed by a senior engineer, from a base in Jaipur with 100+ production apps delivered. We see digital banking app development in UK as a layered job, and vibe coding for building societies and challengers as most valuable around the core: portals, mobile front ends and staff tools.
2. Can vibe coding be used for banking software?
Short answer: yes, for the right layers, under the same controls you would demand from any supplier. UK regulators do not ban AI-assisted development. They test whether you understand your risks, can evidence your controls and remain accountable for your suppliers. Used well, vibe coding for building societies and challengers shortens the path from idea to working prototype, so decisions are made on something real. Before you hire vibe coders for banking software in UK work, decide which layers you are buying speed for.
2.1 What can the AI safely own?
Interfaces, journeys, dashboards, notifications and internal tools. The AI drafts them, a human reviews them and tests prove them. Posting logic, balances, interest and payment authorisation stay with the core platform or with code held to a far higher standard. That split is the backbone of safe digital banking app development in UK.
2.2 Which red and green flags should buyers watch for?
Green flags:
- The agency names the layers it will and will not vibe code
- Every change goes through reviewed pull requests with recorded approvals
- Developers work on synthetic data, with production access limited and logged
Red flags:
- Promises to rebuild a core or ledger in weeks
- No written AI-use policy
- Vague answers on where code, prompts and data are stored
2.3 What should the first 30 days look like?
Week one: agree scope, layers and review rules. Weeks two and three: build a clickable prototype on synthetic data and put it in front of staff. Week four: security review of the prototype, a written plan for integration and a go or no-go decision. A supplier of vibe coding for building societies and challengers that cannot describe this rhythm has not done it before, and it is the first test when you hire vibe coders for banking software in UK work. Strong digital banking app development in UK starts with learning, not with a big build.
3. Which banking components suit vibe coding best?
Short answer: anything customer-facing or staff-facing that sits above the core. Onboarding journeys, account and savings views, card controls, secure messaging, document upload, complaints forms and back-office workflows all fit. Components that decide whether money moves, such as payment authorisation, ledger posting and interest calculation, suit vibe coding least. A supplier you consider when you hire vibe coders for banking software in UK projects should say this unprompted. Vibe coding for building societies and challengers pays off fastest where journeys change often and examiners can see the result.
3.1 Can vibe coders build staff dashboards and portals?
Yes, and they make a low-risk starting point. Start read-only on masked data, apply role-based access and log every action. Many teams doing digital banking app development in UK begin with staff tools for exactly this reason.
3.2 Can vibe coders build savings and mortgage journeys?
Yes, as front ends. Forms, eligibility checks, document upload and progress tracking suit rapid iteration, and vibe coding for building societies and challengers shines here because journeys can be tested with real members quickly. Pricing, affordability decisions and credit rules must come from your approved systems, not from generated code. Ask any digital banking app development in UK supplier how decisions are separated from screens.
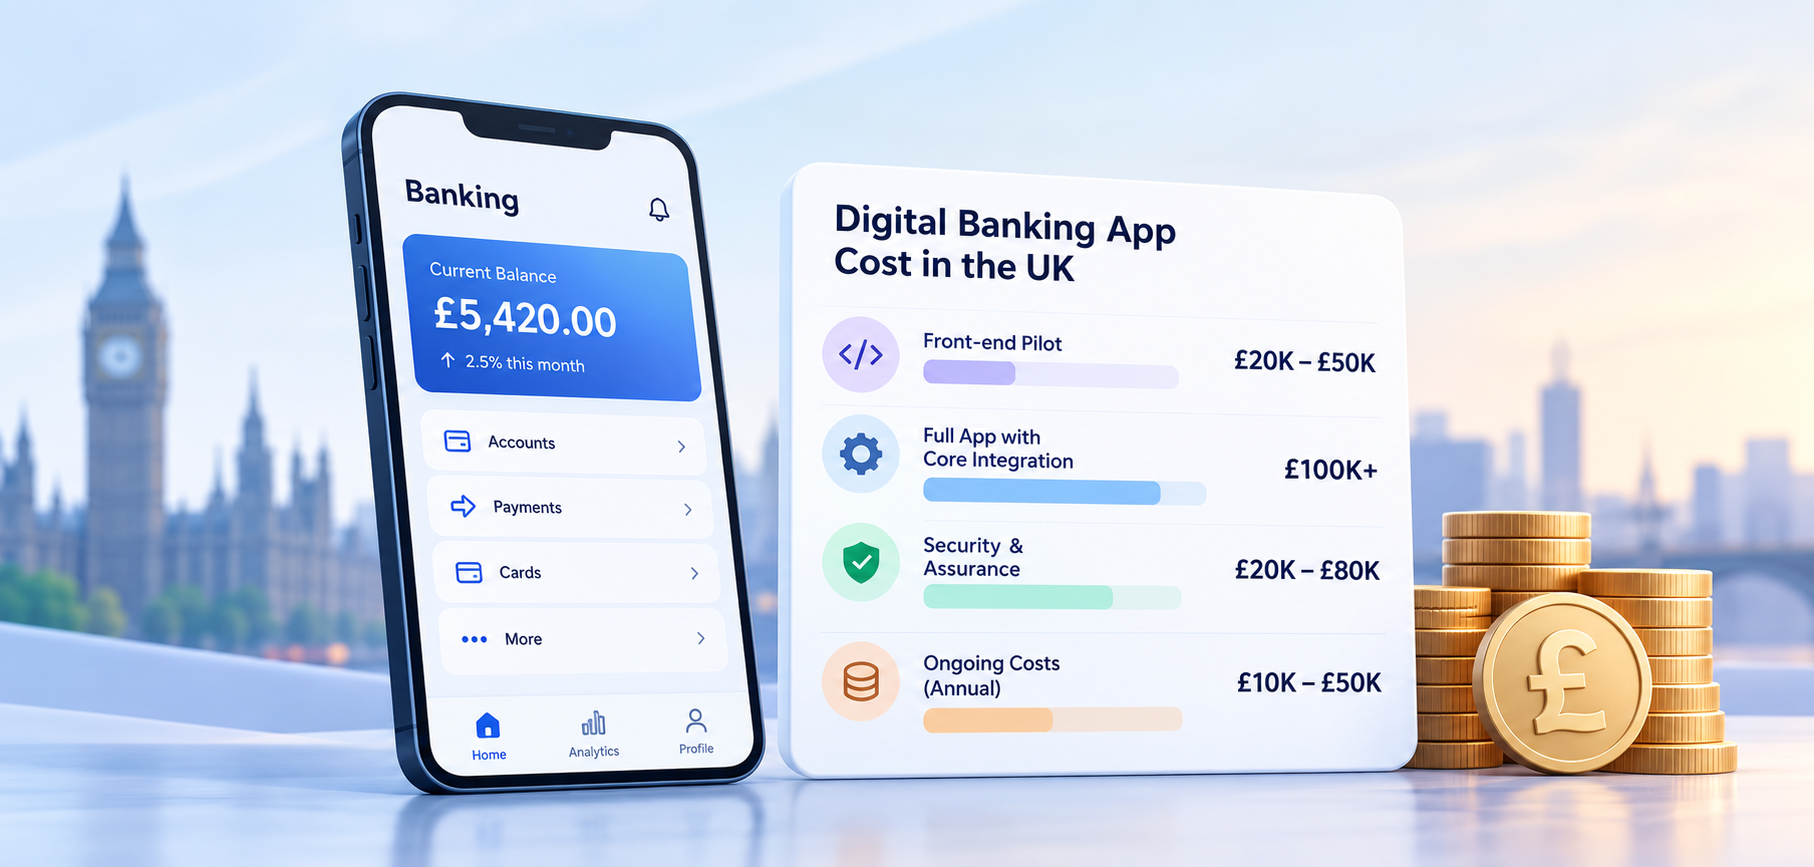
4. How much does a digital banking app cost in the UK?
Short answer: a front-end pilot typically costs tens of thousands of pounds, and a full retail app with payments and core integration moves towards six figures and well beyond. Vibe coding compresses interface work, not assurance. Integration, security testing, accessibility, resilience and regulatory documentation still take time. Ask for quotes in pounds, split into build, integration, assurance and running costs, and compare like for like when you hire vibe coders for banking software in UK work from several suppliers. Honest digital banking app development in UK pricing shows where AI saves money and where it does not.
4.1 How long does a banking MVP take?
A working prototype takes days or weeks. A pilot connected to a core takes months, because supplier onboarding, security review, internal change boards and any regulator notification run on their own timetables. Run these in parallel and pilot with staff first. Ask suppliers of vibe coding for building societies and challengers for a plan where each external dependency has its own line.
4.2 How should you structure a pilot budget?
Fund the build, a testing buffer, assurance work and three months of running costs, then hold a contingency for supplier changes. Pilots reveal surprises, and vibe coding for building societies and challengers keeps the cost of responding low if the budget leaves room. Agree scope in writing before you hire vibe coders for banking software in UK work, so extra requests do not quietly become extra invoices.
4.3 What costs hide outside the quote?
Core vendor API fees, penetration tests, accessibility audits, cyber insurance and monitoring. Any supplier of digital banking app development in UK should list them in its proposal.
5. What regulations apply to UK banking software?
Short answer: it depends on your permissions, but expect the PRA and FCA to sit behind every decision. Core expectations include:
- Operational resilience: identify important business services and stay within impact tolerances
- Outsourcing and third-party risk: PRA SS2/21 and FCA SYSC 8, covering due diligence, audit rights and exit plans
- Consumer Duty: journeys that support good customer outcomes
- Senior Managers and Certification Regime: named accountability
- UK GDPR and the Data Protection Act 2018: lawful, secure processing
- Payment Services Regulations 2017: strong customer authentication
Put compliance and risk teams in the room before the first sprint. A supplier cannot give legal advice, but a good one builds evidence into the product. If you hire vibe coders for banking software in UK work, ask which of these they have designed for, because digital banking app development in UK touches all of them.
5.1 Is AI-written code acceptable to regulators?
No UK regulator has banned it, and at the time of writing none has set separate rules just for it. They apply existing expectations: accountability under the Senior Managers regime, resilience, supplier oversight and sound development practice. In effect a named senior manager owns the outcome, so you need an AI-use policy, independent code review, scanning and a record of which changes were AI-drafted. Vibe coding for building societies and challengers is acceptable when it sits inside those controls.
5.2 How do I manage third-party supplier risk?
Treat your agency as an outsourcing arrangement and apply proportionate due diligence. Check finances, certifications, insurance, subcontractors and data locations. Put access, audit and information rights, incident notification, termination and exit assistance into the contract. For material arrangements, expect to notify your regulator before committing. Ask which AI tools the agency uses and where prompts and code travel. Do this before you hire vibe coders for banking software in UK work, and review it annually.
5.3 What does the Consumer Duty mean for banking journeys?
Customers should understand what they are doing and be able to get help. In an app that means plain language, tested journeys, easy routes to a human and monitoring that shows whether customers succeed. That is where digital banking app development in UK benefits from fast iteration, because wording and flows can be tested in days. Vibe coding for building societies and challengers makes that testing cheap.
5.4 What evidence will auditors ask to see?
Pull request history, test results, scan reports, penetration test findings, approval records and your AI-use policy, organised by release. Teams doing digital banking app development in UK should produce this evidence as a by-product of normal work. If it arrives as a scramble, the process is weaker than the demo suggested, and vibe coding for building societies and challengers will not rescue it.
6. Can vibe coders connect to a core banking platform?
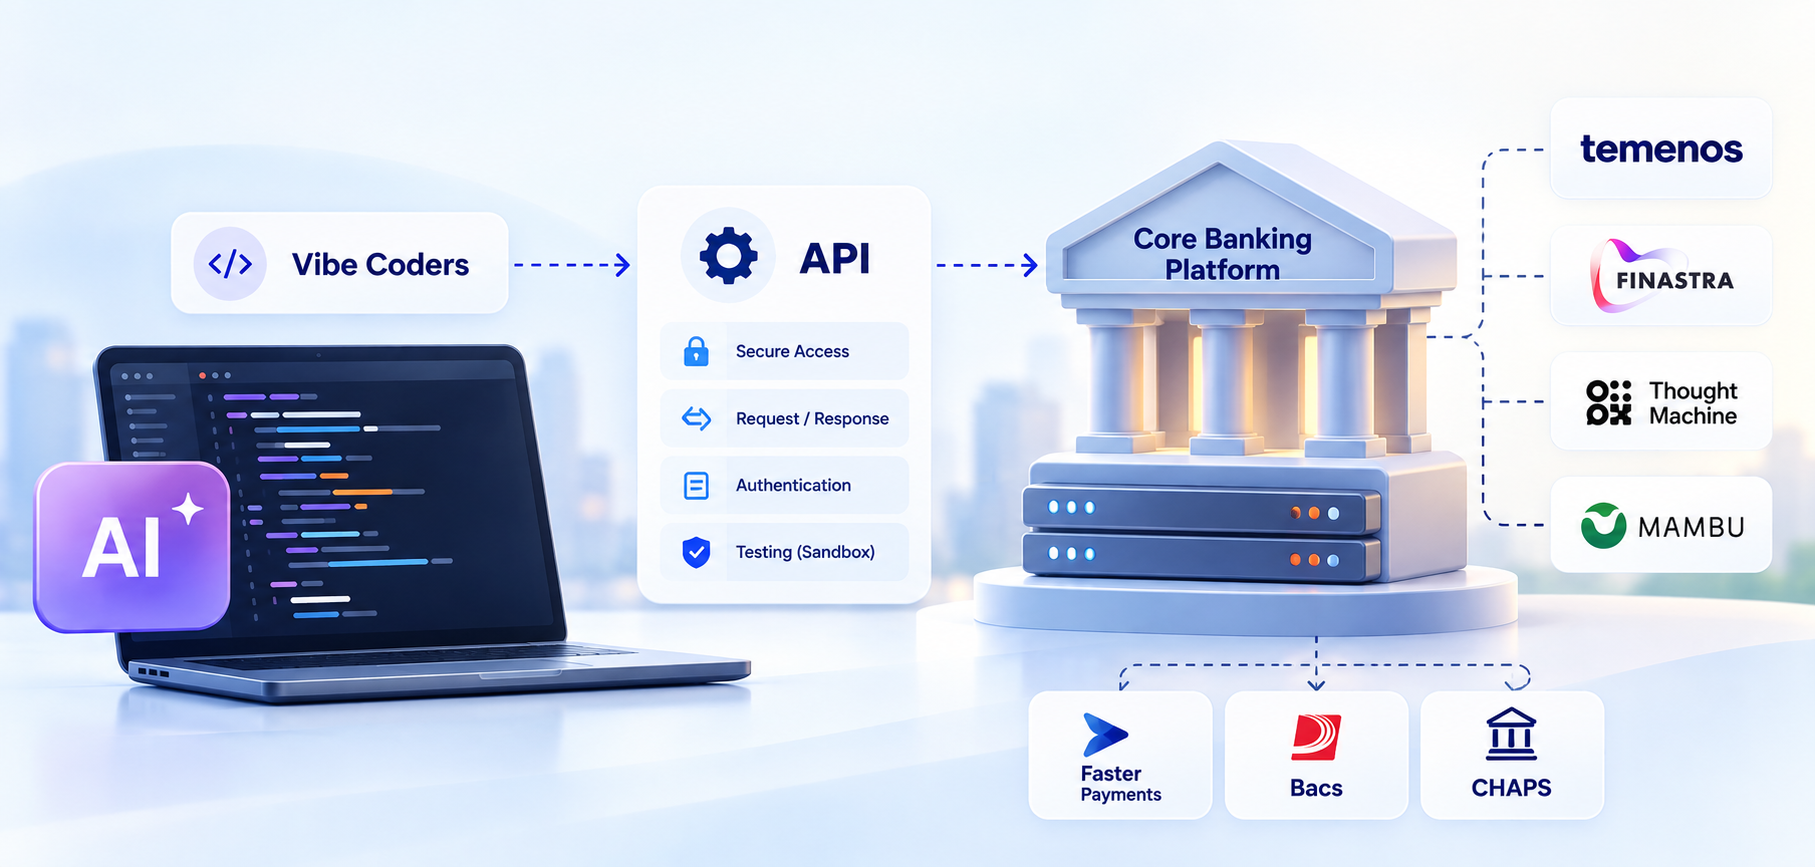
Short answer: yes, through the platform's APIs, with the vendor controlling access. UK institutions run cores from vendors such as Temenos, Finastra, Thought Machine and Mambu, and each has its own onboarding, sandbox and certification routes. Expect credentials, test environments and approval steps before live data. Payment schemes such as Faster Payments, Bacs and CHAPS are reached through your core or a sponsor, not directly from an app.
Vibe coders can build the integration layer against documented APIs, yet timeouts, holds, reversals and batch windows need real testing. Before you hire vibe coders for banking software in UK work, ask which platforms the team has integrated, because vibe coding for building societies and challengers moves fast only when the core is understood.
6.1 What security testing is needed before go-live?
Plan on threat modelling, static and dynamic analysis, dependency and secrets scanning, a penetration test by a CREST-accredited provider, cloud configuration review, resilience tests against your impact tolerances and an accessibility audit. Serious digital banking app development in UK treats this as a gate, not a courtesy.
6.2 How should you test integrations before real money moves?
Use vendor sandboxes, replay real-world edge cases such as duplicate requests and delayed responses, and run staff-only pilots first. Reconcile every test against the core. Before you hire vibe coders for banking software in UK work on integrations, ask to see the test plan, since vibe coding for building societies and challengers is fastest when one exists.
7. How do I meet PSD2 and strong customer authentication rules?
Short answer: authenticate customers with at least two independent factors for online account access and electronic payments, unless an exemption applies. The Payment Services Regulations 2017 set the rule: something the customer knows, has or is. Remote payments also need dynamic linking, which ties authentication to the amount and payee. An app can deliver this with a device-bound key plus a PIN or biometric, covering possession and inherence.
Build this into the first architecture rather than as an add-on, since digital banking app development in UK that retrofits it usually rebuilds login. When you hire vibe coders for banking software in UK work, ask whether the team has shipped these journeys, and how vibe coding for building societies and challengers handles fallbacks and recovery.
7.1 What fallbacks should the journey include?
Plan for lost phones, failed biometrics, expired devices and customers who cannot use a smartphone. Offer a secure phone or branch route. Suppliers of digital banking app development in UK often under-design this, and when you hire vibe coders for banking software in UK work, ask how recovery is protected from fraud.
8. Conclusion
UK banking rewards suppliers who can prove control. Vibe coding gives you speed on the layers around the core, and the PRA and FCA expectations decide how far that speed can go. Keep money logic reviewed to a higher standard, document every AI-assisted change and design journeys for strong authentication and the Consumer Duty. That is how digital banking app development in UK earns confidence from boards and examiners. When you hire vibe coders for banking software in UK work, judge them on evidence, and expect vibe coding for building societies and challengers to come with controls attached.
9. FAQs
Should a building society build or buy?
Buy when you need speed and broad regulatory coverage, build when the member experience is what sets you apart, and mix the two where you can: a bought platform with custom modules around it. Mutuals often gain most from custom onboarding, mortgage and savings journeys, where vibe coding for building societies and challengers suits the custom modules.
What tech stack suits a modern banking app?
A typed backend language such as Kotlin, Java or TypeScript, a relational database, an API gateway, UK-region cloud hosting, managed keys, strong observability and a web or mobile front end. Pick what your team can support and your auditors can follow, especially for digital banking app development in UK.
How do I add biometric login?
Use the phone's built-in biometrics, such as Face ID, Touch ID or Android's biometric prompt, to unlock a device-bound cryptographic key, or adopt passkeys. Never store biometric data yourself, and design a secure fallback and recovery route. Before you hire vibe coders for banking software in UK work on login, ask whether the team has shipped it.
How does ArixLabs approach banking work?
ArixLabs focuses on the layers around the core, such as portals, mobile front ends and staff tools, built with vibe coding and senior review of every change. We map the integration boundary first, design journeys around strong authentication and the Consumer Duty, keep developers on synthetic data and hand you code you own. If you plan to hire vibe coders for banking software in UK projects, ask for our review process before you commit.

View more blogs




Ready to develop your own product? Get in touch today!
Get in Touch